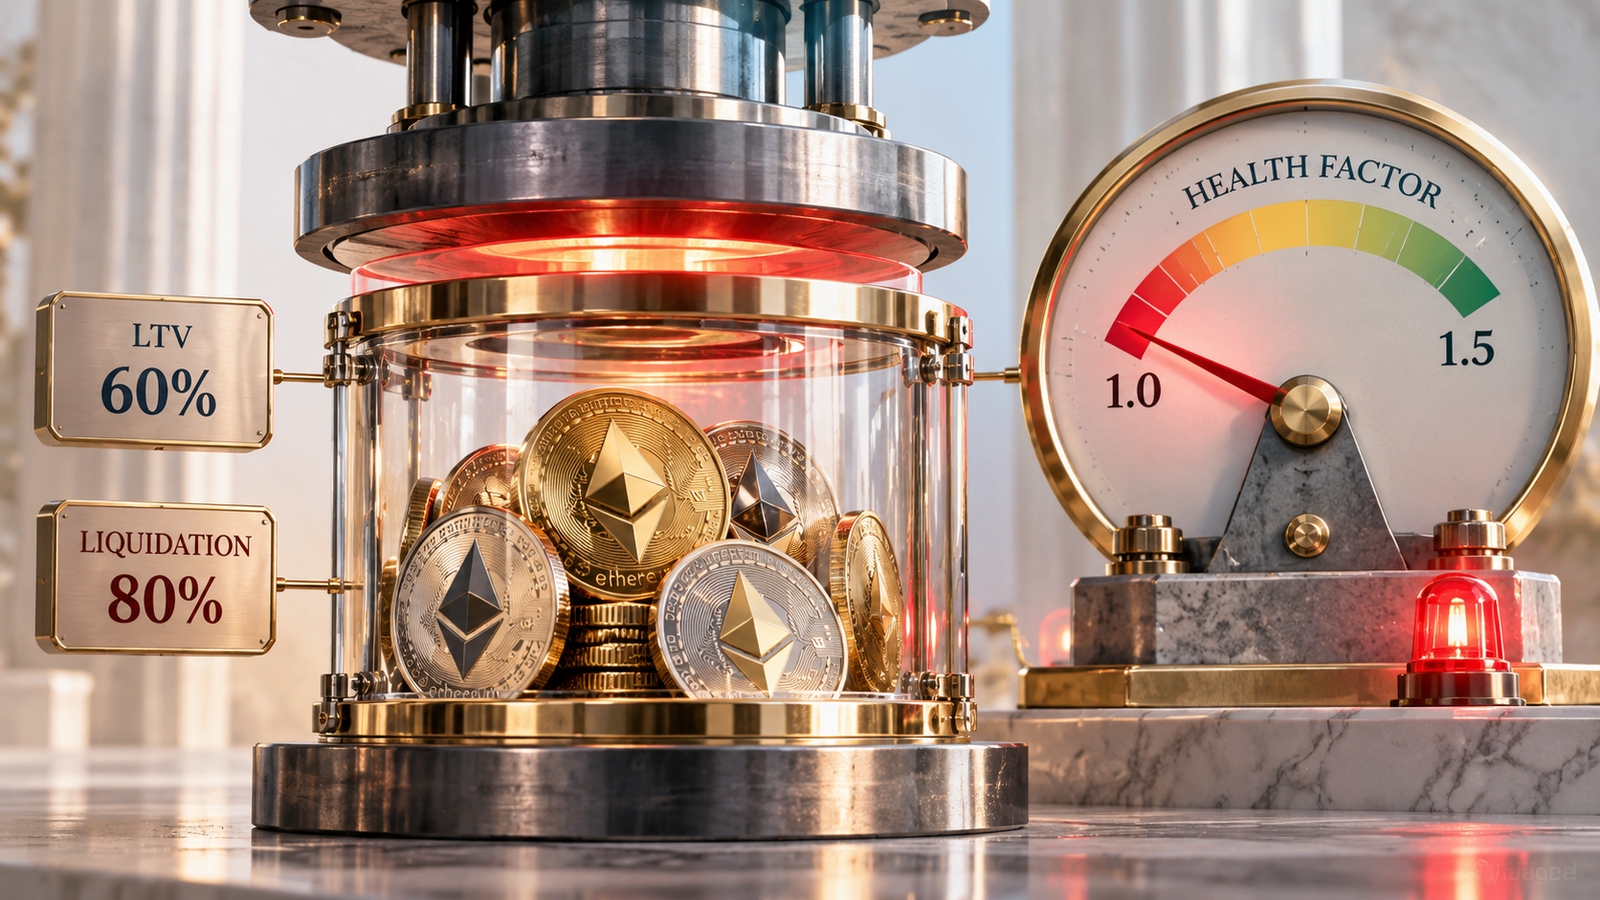
Borrowing $6,000 against $10,000 worth of ETH may look conservative. You still have $4,000 of equity in your collateral, and the loan is overcollateralized. Yet a 25% decline in ETH could bring the position to its liquidation threshold.
DeFi lending protocols don’t wait until collateral becomes worth less than the outstanding debt. They enforce risk limits designed to protect lenders from insufficient collateral.
Three measurements determine how close a borrowing position is to that limit: loan-to-value (LTV), liquidation threshold, and health factor.
Understanding how they interact makes it possible to estimate liquidation prices, measure the impact of falling collateral values, and identify when a loan needs attention.
What Is DeFi Liquidation?
DeFi liquidation is the process of using a borrower’s collateral to repay some or all of an outstanding loan when the position no longer satisfies a protocol’s collateral requirements.
Consider a user depositing ETH into a lending protocol and borrowing USDC against it.
The ETH remains pledged as collateral. The user receives USDC but also assumes an obligation to repay the borrowed amount plus accrued interest.
If ETH loses value, the collateral may eventually become insufficient under the protocol’s risk parameters.
At that point, a third party can initiate a liquidation transaction, repaying eligible debt and receiving collateral in return.
The liquidator typically receives a bonus, which compensates for transaction costs, price risk, and execution.
Liquidation is generally enforced through smart contracts rather than a bank or broker contacting the borrower.
Depending on the protocol, the borrower may lose part or all of the pledged collateral.
What Is Loan-to-Value (LTV) in Crypto?
Loan-to-value measures the size of a loan relative to the current value of its collateral.
The formula is:
LTV = Outstanding Debt / Collateral Value × 100
Suppose a user deposits $10,000 in ETH and borrows $6,000 USDC.
LTV = $6,000 / $10,000 × 100 = 60%
The position has a 60% LTV.
If ETH declines while the USDC debt remains approximately constant, LTV rises.
A higher LTV means the borrower has less collateral backing each dollar of outstanding debt.
How LTV Changes When Collateral Falls
| ETH Price Change | Collateral Value | Outstanding Debt | Current LTV |
|---|---|---|---|
| 0% | $10,000 | $6,000 | 60.00% |
| -10% | $9,000 | $6,000 | 66.67% |
| -15% | $8,500 | $6,000 | 70.59% |
| -20% | $8,000 | $6,000 | 75.00% |
| -25% | $7,500 | $6,000 | 80.00% |
| -30% | $7,000 | $6,000 | 85.71% |
The debt is assumed constant, and USDC is valued at $1 throughout the example.
The important point is that LTV rises even when the borrower takes out no additional loans.
Price movements alone can push a position toward liquidation.
LTV vs Liquidation Threshold: What’s the Difference?
The maximum borrowing LTV and the liquidation threshold serve different purposes.
Maximum LTV determines how much a user can initially borrow against eligible collateral.
The liquidation threshold specifies when the collateral position becomes insufficient under the protocol’s rules.
These two percentages are not necessarily equal.
For example, a lending market might set:
- Maximum borrowing LTV: 75%
- Liquidation threshold: 80%
A user depositing $10,000 could initially borrow up to $7,500 under the simplified maximum LTV calculation.
However, the position becomes eligible for liquidation when its outstanding debt exceeds 80% of its adjusted collateral value, subject to the protocol’s health-factor rules.
The 5-percentage-point difference does not provide a large safety margin for a highly volatile asset.
A borrower using the full permitted LTV can face liquidation after a relatively small adverse move.
Borrowing Parameters Compared
| Parameter | Example Value | Main Purpose |
|---|---|---|
| Collateral deposit | $10,000 | Assets securing the loan |
| Maximum LTV | 75% | Limits initial borrowing capacity |
| Maximum initial borrow | $7,500 | Amount available under the LTV limit |
| Liquidation threshold | 80% | Defines the collateral risk boundary |
| Actual borrowed amount | $6,000 | Determines current exposure |
These are illustrative parameters, not the current configuration of a particular ETH lending market.
Protocols may also impose borrowing caps, efficiency modes, asset restrictions, and other limitations.
What Is Health Factor in DeFi?
Health factor is a risk indicator showing how much room remains before a borrowing position becomes eligible for liquidation.
In Aave-style lending markets, the standard calculation is:
Health Factor = (Collateral Value × Weighted Average Liquidation Threshold) / Outstanding Debt
For a position containing one collateral asset, the weighted average liquidation threshold is simply that asset’s applicable threshold.
The result is expressed as a number.
A health factor above 1 indicates that the position remains above its liquidation boundary under the current calculation.
At 1, the position has reached that boundary.
Below 1, the position is generally eligible for liquidation.
Health Factor Calculation Example
Assume:
- ETH collateral: $10,000
- USDC debt: $6,000
- Liquidation threshold: 80%
Health Factor = ($10,000 × 0.80) / $6,000
Health Factor = 1.33
The position has some room for collateral depreciation, but that margin is smaller than the health factor alone might suggest.
Health Factor Warning Levels
| Health Factor | Risk Interpretation | Suggested Response |
|---|---|---|
| Above 2.00 | Larger collateral buffer | Continue monitoring |
| 1.50–2.00 | Moderate buffer | Review volatility and borrowing costs |
| 1.20–1.50 | Reduced buffer | Consider risk-reduction measures |
| 1.05–1.20 | Close to liquidation | Prioritize collateral and debt review |
| 1.00–1.05 | Minimal remaining buffer | Urgent attention |
| Below 1.00 | Liquidation eligibility | Liquidation may already be possible |
These are illustrative monitoring bands, not official protocol safety ratings.
There is no universally safe health factor. A position backed by highly volatile collateral may require considerably more room than one involving strongly correlated assets.
Borrowing rates, oracle movements, and market liquidity can also change the risk profile.
DeFi Liquidation Example: ETH Falls 25%
Return to the $10,000 ETH collateral position with $6,000 borrowed.
Assume the liquidation threshold remains 80%.
If ETH falls by 25%, the collateral value declines to $7,500.
Health Factor = ($7,500 × 0.80) / $6,000 = 1.00
The position has reached its modeled liquidation boundary.
A further decline would push the health factor below 1, making it eligible for liquidation under the assumed rules.
How Falling ETH Changes Liquidation Risk
| ETH Price Change | Collateral Value | LTV | Health Factor |
|---|---|---|---|
| 0% | $10,000 | 60.00% | 1.33 |
| -10% | $9,000 | 66.67% | 1.20 |
| -15% | $8,500 | 70.59% | 1.13 |
| -20% | $8,000 | 75.00% | 1.07 |
| -25% | $7,500 | 80.00% | 1.00 |
| -30% | $7,000 | 85.71% | 0.93 |
This calculation assumes no additional collateral, debt repayment, interest accrual, oracle differences, or protocol parameter changes.
In reality, the position could approach liquidation earlier as borrowing interest accumulates.
The example also demonstrates why waiting until health factor reaches 1.05 can be dangerous. A relatively small additional price move may be enough to cross the threshold.
How to Calculate Your DeFi Liquidation Price
For a simple position with one collateral asset and debt denominated in a stable asset, liquidation price can be estimated using:
Liquidation Price = Outstanding Debt / (Collateral Quantity × Liquidation Threshold)
Suppose the borrower deposits 4 ETH when ETH trades at $2,500.
The initial collateral value is $10,000.
With $6,000 of USDC debt and an 80% threshold:
Liquidation Price = $6,000 / (4 × 0.80)
Liquidation Price = $1,875 per ETH
ETH falling from $2,500 to $1,875 represents a 25% decline.
This is the modeled liquidation boundary, assuming all other inputs remain unchanged.
For positions backed by multiple collateral assets or containing several debt assets, a single liquidation price may not exist. Different price combinations can cause the health factor to cross 1.
Oracle pricing also matters. The protocol may use a different reference price from the one displayed on a trading exchange.
What Happens During a DeFi Liquidation?
When a position becomes eligible, liquidators can submit transactions that repay part or all of its debt.
In exchange, they receive collateral according to the protocol’s liquidation rules.
Consider a simplified liquidation with:
- Outstanding debt: $6,000
- Debt repaid by liquidator: $3,000
- Liquidation bonus: 5%
The liquidator receives collateral worth approximately:
$3,000 × 1.05 = $3,150
The borrower has $3,000 of debt repaid but loses $3,150 worth of collateral.
The extra $150 represents the liquidation bonus in this simplified calculation.
A liquidation can therefore reduce the borrower’s remaining equity even though outstanding debt also decreases.
The exact amount that can be liquidated varies by protocol, position size, health factor, and version.
For example, certain Aave V3 configurations permit liquidating up to 50% of debt under specified conditions, with larger portions eligible when the position is more severely undercollateralized. Newer liquidation designs may instead aim to restore a target health factor.
Liquidation does not necessarily close the entire loan.
How to Avoid Liquidation in DeFi
Borrowers can reduce liquidation risk by increasing eligible collateral, lowering outstanding debt, or maintaining a larger buffer from the liquidation threshold.
These actions have different economic effects.
1. Repay Part of the Loan
Suppose the original position has $10,000 in collateral and $6,000 in debt.
Repaying $2,000 lowers the debt to $4,000.
New Health Factor = ($10,000 × 0.80) / $4,000 = 2.00
The position now has substantially more room before liquidation.
Repayment generally provides a direct reduction in debt exposure.
2. Add More Collateral
Alternatively, suppose the borrower adds another $2,000 of eligible collateral with the same liquidation threshold.
The new collateral value is $12,000.
New Health Factor = ($12,000 × 0.80) / $6,000 = 1.60
This also improves the position, but not as much as the $2,000 debt repayment in the example.
Comparing Risk-Reduction Strategies
| Action | Collateral Value | Debt | Health Factor |
|---|---|---|---|
| Original position | $10,000 | $6,000 | 1.33 |
| Repay $2,000 | $10,000 | $4,000 | 2.00 |
| Add $2,000 collateral | $12,000 | $6,000 | 1.60 |
These examples assume unchanged prices and eligible collateral parameters.
Adding volatile collateral can improve health factor initially while increasing exposure to future market declines.
3. Monitor Borrowing Interest
Outstanding debt can grow as interest accrues.
Even with stable collateral prices, increasing debt gradually reduces health factor.
Variable borrow rates may also rise sharply when lending market utilization increases.
4. Set Health Factor Alerts
Borrowing dashboards and supported monitoring tools may provide alerts when health factor approaches a chosen level.
Useful warning thresholds can include 1.50, 1.30, and 1.15, depending on the position’s volatility and risk tolerance.
Alerts are only notifications. They cannot guarantee that you will have enough time to act during a market crash.
5. Maintain Available Repayment Liquidity
Keeping accessible funds outside the borrowing position can make emergency debt repayment easier.
However, transaction delays, network congestion, withdrawal restrictions, and asset depegging can interfere with last-minute adjustments.
The safest risk controls are usually established before volatility increases.
Why Liquidations Can Happen Faster Than Expected
Several factors can cause a position to deteriorate unexpectedly.
Collateral prices may gap lower during thin trading conditions.
Borrowed asset prices can rise relative to collateral. For example, a borrower owing ETH against another cryptocurrency faces increased debt value if ETH appreciates.
Interest accrual can gradually increase debt.
Oracle updates can also change the collateral valuation used by the lending protocol.
In extreme market conditions, liquidation bots may react before a user can manually repay or add collateral.
For borrowers, the practical lesson is that health factor should be monitored as a changing exposure, not a static number established when the loan was opened.
Frequently Asked Questions
What triggers liquidation in DeFi?
In many lending protocols, liquidation becomes possible when collateral value falls sufficiently or debt increases enough to push the health factor below 1.
What does a health factor of 1.2 mean?
It indicates that the risk-adjusted collateral value is 1.2 times the outstanding debt under the applicable formula. The position still has a buffer, but the actual tolerable price decline depends on its collateral and debt composition.
Is 1.5 a safe health factor?
It may provide a reasonable buffer in some circumstances, but there is no universal safety threshold. Asset volatility, liquidation parameters, debt growth, and correlation matter.
What is the difference between LTV and liquidation threshold?
LTV measures current debt relative to collateral. Maximum borrowing LTV limits borrowing capacity, while the liquidation threshold determines when collateralization becomes insufficient under the protocol’s rules.
Can you lose all your collateral during liquidation?
Yes, depending on protocol rules and the severity of the position’s deterioration. Some liquidations are partial, while others can remove most or all collateral.
Can I prevent liquidation by adding more collateral?
Adding eligible collateral generally improves health factor, but it does not guarantee protection against further price declines. Repaying debt can also improve the position.
Can liquidation happen without a major crypto price crash?
Yes. Debt interest, changes in borrowed asset prices, collateral depegging, oracle prices, and protocol parameters can affect liquidation eligibility even without a broad market crash.
Does a health factor below 1 mean liquidation has already happened?
No. It generally means the position is eligible for liquidation. Actual execution requires a successful liquidation transaction, and the process depends on the protocol’s rules.